 by
Anti-Money Laundering (AML) and Countering Financing of Terrorism (CFT) legislation significantly impacts the New Zealand real estate sector, encompassing both property purchases and commercial leases. The primary aim of the AML/CFT Act 2009 is to detect and deter money laundering and terrorism financing, thereby protecting New Zealand’s financial system and international reputation.
The Scope of AML/CFT in NZ Real Estate
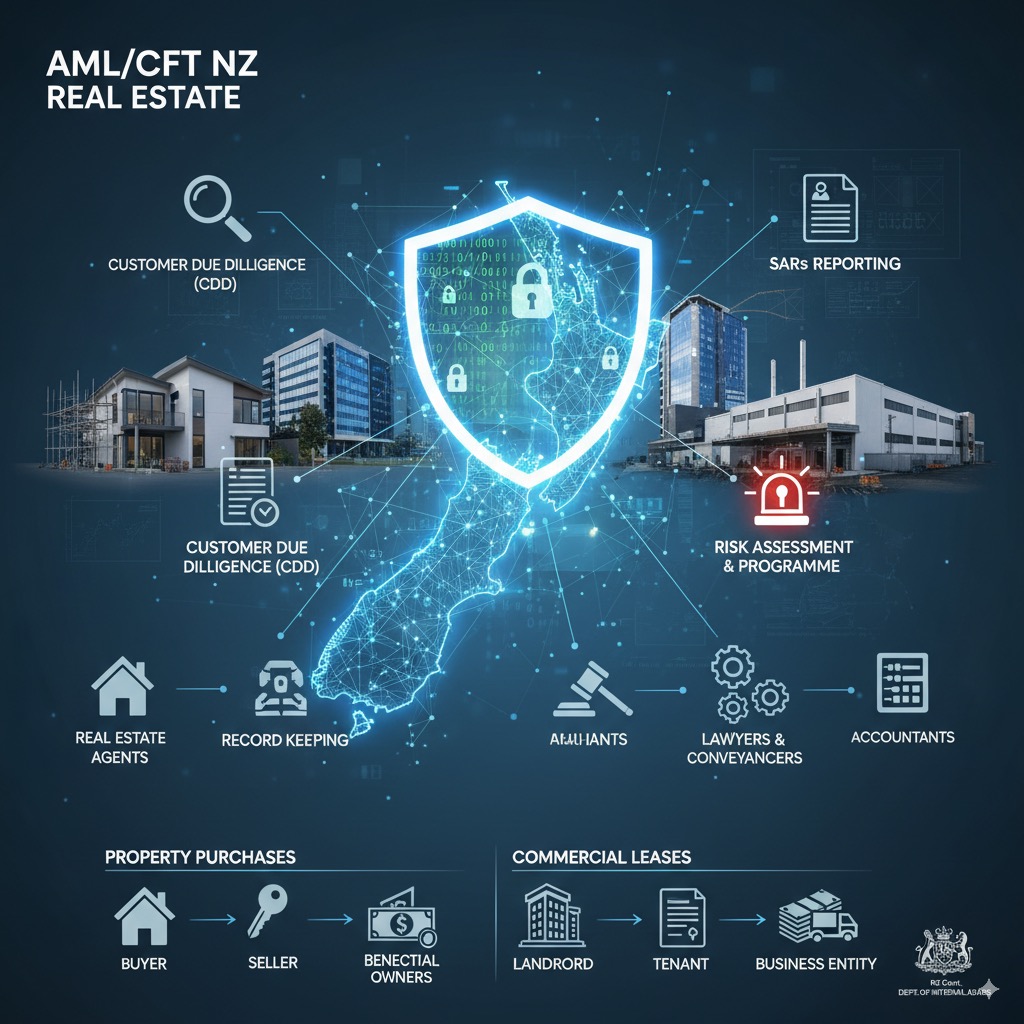
Initially, the AML/CFT Act focused on financial institutions. However, its scope expanded in phases, bringing “Phase 2” entities under its obligations. Real estate agents were included in this expansion, with their obligations coming into effect on 1 January 2018. This means that anyone involved in the buying, selling, or leasing of property, who falls under the definition of a “reporting entity,” must comply with the Act.
Reporting Entities in Real Estate:
- Real Estate Agents: Licensed real estate agents are unequivocally reporting entities.
- Lawyers and Conveyancers: These professionals are also reporting entities and play a critical role in property transactions.
- Accountants: While not directly involved in property sales, accountants may be caught by AML/CFT obligations if they advise on property investments or manage funds related to real estate.
Key AML/CFT Obligations for Real Estate Professionals
Reporting entities in the real estate sector have several core obligations:
- Conduct a Risk Assessment: Each reporting entity must conduct a comprehensive risk assessment to identify and understand the money laundering and terrorism financing risks they face. This assessment should consider the nature of their business, the types of customers they deal with, the services they offer (e.g., residential sales, commercial leases, property management), and the countries they transact with.
- Establish an AML/CFT Programme: Based on the risk assessment, an AML/CFT programme must be developed. This programme outlines the policies, procedures, and controls the entity will implement to mitigate the identified risks. It should cover:
- Customer Due Diligence (CDD): The process of identifying and verifying the identity of customers.
- Record Keeping: Maintaining records of all CDD and transaction information.
- Reporting Suspicious Activities (SARs): Notifying the Police Financial Intelligence Unit (FIU) of any suspicious transactions or activities.
- Compliance Officer: Appointing a designated person responsible for overseeing AML/CFT compliance.
- Staff Training: Ensuring all relevant staff are trained on AML/CFT obligations.
- Independent Audit: Having the AML/CFT programme independently audited every two years.
- Customer Due Diligence (CDD): This is perhaps the most visible and impactful obligation for clients. Real estate agents must perform CDD on:
- Vendors (Sellers): The individuals or entities selling a property.
- Purchasers (Buyers): The individuals or entities buying a property.
- Landlords (Lessors): In the context of commercial leases, the property owners.
- Tenants (Lessees): In the context of commercial leases, the individuals or entities entering into the lease.
- Standard CDD: Required for most customers and involves verifying identity (e.g., passport, driver’s license), address, and understanding the nature and purpose of the business relationship. For individuals, this means proof of ID and address. For companies, it involves verifying the company’s existence, its directors, and beneficial owners (individuals who ultimately own or control the company).
- Simplified CDD: Can be applied in low-risk situations, where the risk assessment indicates a reduced likelihood of money laundering or terrorism financing.
- Enhanced CDD: Mandated for high-risk customers or transactions. This includes situations involving politically exposed persons (PEPs), customers from high-risk jurisdictions, or complex ownership structures. Enhanced CDD requires more rigorous verification and ongoing monitoring.
Impact on Property Purchases
For property purchases, both the buyer and seller will undergo CDD by their respective real estate agents and legal representatives.
- For Buyers: Expect to provide identification, proof of address, and potentially information about the source of funds for the purchase. If buying through a trust or company, additional documentation for trustees, directors, and beneficial owners will be required.
- For Sellers: Similar CDD will be conducted to verify their identity and ensure the legitimacy of the transaction.
- Beneficial Owners: A significant focus is on identifying beneficial owners – the individuals who ultimately own or control an entity, even if the property is registered in the name of a company or trust. This prevents individuals from hiding their identities behind complex structures.
Impact on Commercial Leases
The application of AML/CFT to commercial leases is equally important, though often less understood by those unfamiliar with the regulations.
- When AML Applies to Leases: Real estate agents acting as intermediaries in commercial lease transactions are caught by the AML/CFT Act. This means both the prospective landlord and tenant will be subject to CDD.
- Nature of the Relationship: While a lease might seem less like a “transaction” in the traditional sense, it establishes an ongoing business relationship, which triggers AML/CFT obligations.
- CDD for Landlords and Tenants:
- Landlords: Will need to provide identification and proof of address. If the property is owned by a company or trust, the beneficial owners will need to be identified.
- Tenants: Similar to landlords, individuals will need to provide ID and address verification. Companies and trusts will require documentation for directors, trustees, and beneficial owners. The nature of the tenant’s business and its activities will also be considered as part of the risk assessment.
- Ongoing Monitoring: For long-term commercial leases, ongoing monitoring of the business relationship may be required, particularly if the risk assessment indicates a higher risk.
Challenges and Best Practices
Challenges:
- Client Understanding: Clients can sometimes find the CDD process intrusive or confusing.
- Complex Structures: Dealing with trusts, companies, and international entities can make CDD challenging.
- Time Delays: Gathering all necessary documentation can cause delays in transactions.
- Maintaining Compliance: Staying up-to-date with evolving regulations and ensuring consistent application across all staff.
Best Practices:
- Early Communication: Inform clients early in the process about AML/CFT requirements and what information they will need to provide.
- Clear Policies and Procedures: Have robust internal policies and procedures for CDD, record-keeping, and reporting.
- Utilise Technology: Employing identity verification software and other AML/CFT solutions can streamline the process.
- Ongoing Training: Regularly train staff on AML/CFT obligations and any updates to the legislation.
- Professional Advice: Seek advice from legal and AML/CFT compliance specialists to ensure ongoing compliance.
The Role of Regulators
The Department of Internal Affairs (DIA) is the primary AML/CFT supervisor for the real estate sector. They monitor compliance, provide guidance, and have the power to impose penalties for non-compliance.
Conclusion
The AML/CFT Act has fundamentally reshaped operations within the New Zealand real estate sector. While imposing significant compliance burdens, it is a crucial framework for safeguarding the integrity of property transactions and commercial leases. For both real estate professionals and their clients, understanding and adhering to these obligations is not merely a legal requirement but a vital contribution to combating financial crime in New Zealand.
Disclaimer:
The information provided in this article is general in nature and should not be considered as legal, financial, or professional advice. Buyers/sellers are strongly encouraged to seek independent legal and/or financial advice from qualified professionals before making any decisions related to property transactions.
Join The Discussion